
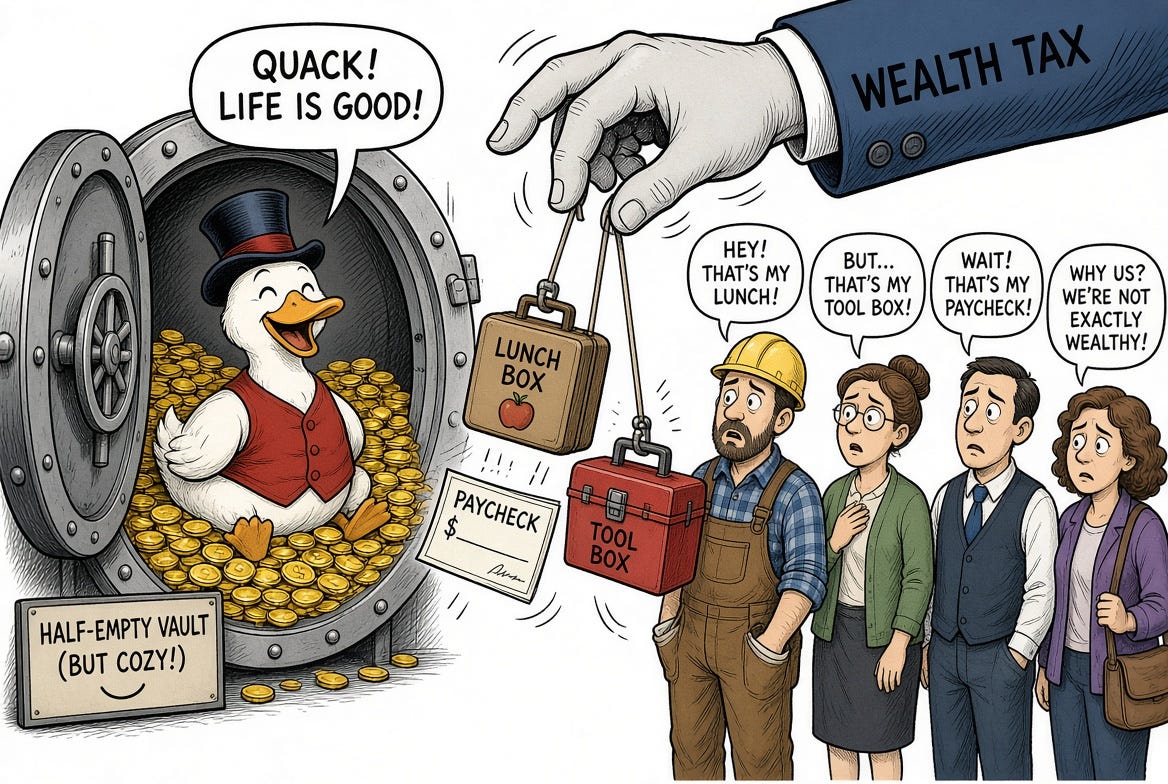
The pitch is always the same, and it is always seductive.
Somewhere out there is a pile. A great, glittering, obscene pile of money, and a small number of people are sitting on top of it doing nothing useful. The pile just sits there, the way piles do, while teachers buy their own classroom supplies and the bridge falls into the river. So we will reach into the pile — just once, just a little, just the tip of it — and we will use what we take to do some good. A wealth tax. A mark-to-market tax on unrealized gains. Capital gains taxed as ordinary income. The mechanism varies; the picture underneath it never does. There is a pile, the pile is static, and reaching into it costs no one anything except the people who have more than they could ever need.
I want to tell you why this picture is wrong. Not wrong in the sense that reasonable people disagree about the rate. Wrong in the sense that the central object in the picture — the static pile you can dip into without consequence — does not exist, and the thing that does exist behaves nothing like it. And I want to do it without the usual libertarian throat-clearing, because the usual libertarian throat-clearing is exactly what lets the people who love these taxes wave the whole argument away as ideology. So let me grant them everything. Let me grant that the inequality is real, that the need is real, and grant, charitably, that the concern for the poor is entirely sincere. None of that is the problem. The problem is that the instrument does not do what they think it does, and the cleanest way to see it is to try to tax a cartoon duck.
The duck
Scrooge McDuck has a money bin. You remember it: a building-sized vault filled to the rafters with gold coins, into which the richest duck in the world dives each morning for a swim. It is the platonic ideal of the pile. If you have ever felt the intuition that we should tax great fortunes, you have felt it about that money bin. There it sits. Tax it.
So tax it. Walk into the bin, take a fifth of the coins, walk out. What just happened?
Nothing happened. Or rather: nothing happened to anyone but Scrooge. The coins in the bin were not doing anything. They were not financing a factory, not paying a wage, not buying a machine, not building a house. They were a hoard — inert, idle, swum-in. Whatever harm you imagined that hoard was doing to the rest of us, it was not doing, because a pile of metal in a vault does not reach into anyone else’s life. You took a fifth of it and you accomplished precisely one thing: the pile is now smaller. The bridge is no closer to being fixed than it was, except to whatever extent the gold you carried out can be spent — and the moment you spend it, you’ve simply moved the pile, not unlocked any productivity that the pile was strangling. There was no strangling. It was a swimming pool.
Here is the part that should stop you, and it is an argument I owe to Steven Landsburg, who made it years ago in a piece called “The Man Who Can’t Be Taxed.” To tax someone is to lower their consumption — that is what bearing the burden of a tax means, in the currency this argument is denominated in, which is real goods and nothing else. (And to keep the point clean, treat the coins as what modern fortunes actually are — entries in a ledger — rather than gold, which is itself a real commodity you can fill teeth with.) If your consumption is unchanged, you have not been taxed in that currency, no matter what the ledger says. So watch what happens when the government empties the bin. Scrooge’s consumption before the seizure was zero; he was swimming in coins, not spending them. His consumption after the seizure is also zero; he’s just swimming in a smaller pool. His consumption did not change. So he bore no burden in consumption terms (other than swimming in a little less gold, which for the purposes of this argument we can consider negligible). But the government now has the coins and will spend them — which means the government consumes more, which means, in an economy that is using its resources, someone else must consume less. And it cannot be Scrooge, because his consumption was zero and stayed zero. So the burden of “taxing the idle rich man” falls not on the idle rich man but on the rest of us, whose share of real goods the government’s new spending bids away. You did not tax Scrooge McDuck. You taxed everyone who isn’t Scrooge McDuck, and sent him the bill addressed to someone else.
That argument runs in a stripped-down model where the only thing wealth is for is consumption — and I want to keep the toy model honest, because the real world is richer. A smaller bin might cost Scrooge something the toy model can’t see: the option to spend later, status, security, political heft, the bequest he meant to leave, the sheer pleasure of the swim. Those are real, and a wealth tax can reach them even when it can’t reach his dinner. But notice what the toy model isolates, which is the whole point: it separates real consumption from accounting claims, and it shows that to the extent a fortune is the latter and not the former, taxing it doesn’t free up goods for anyone — it just moves the claims, and the burden lands elsewhere.
Which means that to whatever extent a real Scrooge McDuck exists — someone sitting on idle wealth, consuming nothing — he is not a problem to be solved. He is the single most harmless rich person imaginable. He produced something, or holds claims on something others produced, and in exchange he has taken nothing out of the common pool. He doesn’t eat your lunch. He doesn’t bid up your house. He doesn’t consume the goods you wanted. His fortune is a number on a ledger and a pile of metal he likes to look at. In pure consumption terms, the miser on his hoard has donated his entire economic output to the rest of us and asked for nothing back. He is, whether he means to be or not, a philanthropist — and you cannot tax a philanthropist by confiscating the gift he has already given.
We will come back to that, because it turns out to be the whole argument. But first the obvious objection, which is correct: real billionaires are not Scrooge McDuck. There is no bin. Elon Musk does not have a swimming pool of dollars. And that is exactly the point, because it means the thing you are actually proposing to tax is not the bin.
There is no bin
Real wealth at the top is not a hoard of coins. It is claims on productive enterprise — shares in companies, stakes in firms. Those claims are not identical to the machines, buildings, software, and organizational knowledge beneath them; a trillion dollars of market capitalization is not a trillion-dollar warehouse of lathes, and equity value bundles factories together with rents, patents, growth expectations, and control. But the claims and the machines are coupled, and the coupling is where all the action is: the valuation of the claims sets the cost of raising capital, which sets what gets financed, which sets the capital each worker has to work with, which sets — more than almost anything else — what those workers get paid. A recurring tax on the claims does not scoop coins from a vault. It changes the terms on which productive assets are financed, owned, and expanded, and the wage effects arrive through that chain. (Someone always objects here that buying a share on the secondary market funds nothing — the “it’s only paper” move. A recent working paper says otherwise, through a channel almost nobody expected: Sammon and Shim find that when index funds buy, the sellers on the other side are, roughly one-for-one, the firms themselves — issuing new equity, largely through stock-based compensation — so two decades of passive buying has financed corporate equity issuance. The paper claims and the real machines are joined more tightly than the objection assumes; the full story deserves its own post.)
This matters because it splits the wealth tax in two, and the tax misses on both halves.
If the wealth is in fact hoarded — the actual bin, idle and consuming nothing — then taxing it releases nothing. You are taking from the one person who, by construction, took nothing from anyone, and the seizure conjures no bridge, no nurse, no machine — it relabels who holds the tickets.
And if the wealth is deployed — which is the real case, the overwhelming case — then it isn’t a bin at all. It’s the capital stock. And now your tax is not a one-time dip into a static pile. It is a recurring wedge driven into the exact machinery that builds future wages. Every year the capital exists, the tax bites again. And that recurrence — not the unfairness, not the politics, the plain arithmetic of a wedge that compounds — is the thing nobody prices in.
Let me show you the number, because this is where assertion turns into arithmetic.
The terminal accounting
One clarification before the arithmetic, because it governs everything after it. The question is never whether to tax. The government is going to spend what it spends, and the revenue has to come from somewhere. What every serious model in this literature actually asks is narrower: which instrument raises a given sum at the lowest cost — capital, labor, or consumption? So nothing below is a claim that taxing capital is bad and taxing nothing would be better. It is a claim that of the three doors available for raising the same dollar, one of them opens onto a wedge that compounds and the other two do not. That is a narrower argument than the one usually made in my direction, and it is the one that survives contact with someone who does this for a living.
One more piece of scope, so nobody gets ambushed later. My target is recurrent taxation of the normal return to deployed capital — annual mark-to-market taxation, recurring wealth levies, and their accrual cousins. Other instruments are different animals with different arithmetic, and I will keep them separate — fold them together and “capital taxation” becomes a suitcase into which every policy dispute has been stuffed. A one-time levy on existing wealth gets its reckoning next week, land and rents get theirs there too, and the realization-based tax with deferral — which is what America actually has — stays labeled as such throughout. The compounding objection applies most directly to the normal return required to make deferring consumption worthwhile. It does not carry over unchanged to land rents, monopoly profits, or windfalls.
Capital is deferred consumption. This is not an ideological statement; it is what capital is. A dollar of capital is a claim on future goods — goods you chose not to consume now so that you (or your kids, or whoever holds the claim later) could consume more of them later. When you tax capital, you are taxing future consumption. You are reaching forward in time and taking a slice of the goods someone was saving for.
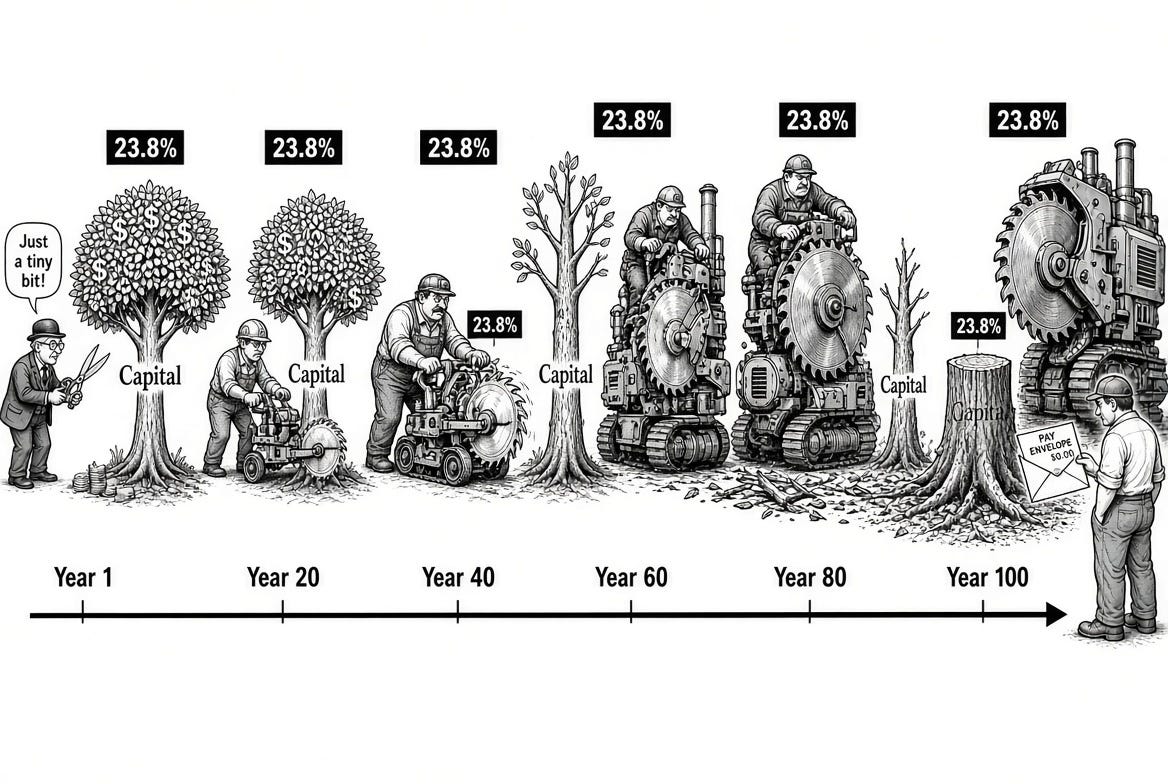
Now run the numbers on what a flat, modest, annual rate does to that future slice — and one piece of precision first, because the precision is the point. The arithmetic that follows describes an annual tax on capital as it accrues: a mark-to-market tax on unrealized gains, a wealth tax, an annual levy on capital income. It is not the ordinary U.S. capital gains tax, which is charged once, at sale, and lets the gain compound untaxed until then. But the annual, accruing form is the architecture of the marquee proposals — Senator Wyden’s plan would mark tradable assets to market and tax the gain annually; the Treasury’s billionaire-minimum design is a gentler cousin that treats the annual payment as a prepayment credited at eventual sale — and it is the annual form, not the realization form, where the compounding catastrophe lives. So I’ll use today’s top capital-gains-plus-NIIT rate as a familiar number, not as a claim that gains are taxed annually today. They are not. The proposals want to change that.
Take that number: twenty percent, plus the 3.8% Net Investment Income Tax, for 23.8% all in. Nobody calls it confiscatory; the people who want to mark gains to market annually consider it gentle. Now levy it every year on a real return of five percent — which is what “tax unrealized gains” means — and ask the only question that matters: of the future consumption you were actually saving for, how much does this “gentle” annual tax remove?
At a one-year horizon, almost nothing — about one percent. Fine. But you don’t save capital for one year; you save it for a life, for a retirement, for a generation. At ten years the tax has eaten about 11% of your future goods. At twenty years, 20%. At thirty years, 29%. At forty years — a working life — the headline rate of 23.8% has become an effective tax of 36.6% on the consumption you were deferring. At fifty years, 43%. And over a hundred years — the horizon a foundation or a family office plans across — a “gentle” 23.8% annual rate becomes a 68% tax on the goods at the far end. The saver was told the government takes 23.8% of his gains. The terminal accounting says the government takes 37% of a working life’s goods, and two-thirds of a century’s. Two words about what that 68% is, because this is where a critic will aim: the state does not collect 68% of the year-hundred account. The statutory rate stays 23.8% of each year’s return, forever; what the accumulated wedge removes is 68% of the consumption available in the untaxed counterfactual. Your wealth still grows. It just grows into a third of what it would have been. (These are also partial-equilibrium numbers. In general equilibrium a smaller capital stock pushes the pre-tax return up, so the individual saver’s realized burden is somewhat lighter than this — in part because some of it has been shifted onto labor, through the lower wages a thinner capital stock pays. How much shifts is model-dependent, but the direction of the correction makes the incidence worse for workers, not better — which is next week’s essay arriving early.)
A recurring wealth tax runs the same machinery with a different dial, and the translation is worth doing because the dial is deceptively marked. A 1% annual tax on wealth is not “only one percent”: against a 5% real return, it absorbs a fifth of the return, every year, whether or not the return shows up. Run it out and a portfolio compounding at 4% instead of 5% lands about 32% below the untaxed path at forty years and 62% below it at a century. The proposals on the table start at 2%, which against the same return is a 40% annual tax on the return before compounding — and the wealth tax collects it in loss years too, which the income tax at least has the manners not to do.
The headline rate never moved. The rate that actually lands climbed the entire way up. Why? Because each year’s tax is itself a brick pulled out of the wall that compounds. You don’t merely lose this year’s skim — you lose every future dollar that this year’s skim would have earned, and every dollar those would have earned, forever. The flat rate is conserved. The thing it taxes grows exponentially in the horizon. So the effective bite has to grow to match. (Readers of The Conservation Law of Tax Alpha will recognize the move: find the quantity that’s conserved, then do the accounting all the way to the end. The fund managers hide the conservation law in the fee structure. The state hides it in the compounding.)
Now the line that should reframe the entire debate. That climb never stops. Run even the gentlest rate anyone seriously proposes — fifteen percent — out far enough and it asymptotes to a one hundred percent tax: about 51% at a century, 97% at five hundred years. For any positive rate, the effective tax on consumption N years out climbs toward total confiscation as N grows. No flat capital tax is gentle enough to spare the far future; give it enough time and it takes essentially all of it. That is not rhetoric. It is the geometry of compound interest, and it is the same for a Marxist and a monk.
One limit on what the asymptote proves, before anyone proves it for me: it establishes persistence, not optimality. A one-percent management fee also compounds toward eating everything, given enough centuries — readers of the Tax Alpha piece watched me run exactly that accounting on the wealth-management industry — and the conclusion there was not that fees must be zero. It was that you must price the compounding before you sign. Same here. The asymptote tells you the wedge never stops mattering; it does not, by itself, pick the rate. Picking the rate still requires weighing everything else — redistribution, risk, what the revenue buys, what the alternative taxes cost. The asymptote is not the verdict. It is the invoice.
The same compounding that makes a flat rate confiscatory over time also dismantles the most popular argument for capital taxes — the Warren Buffett line, the one about how it’s a scandal that the billionaire pays a lower rate than his secretary. The sharpest demolition is again Landsburg’s, in a post called “Getting It Right.” Take Alice and Bob (physicists always reach for Alice and Bob). Both earn a dollar of wages and both pay a 50% wage tax, leaving each with fifty cents. Alice spends her fifty cents immediately. Bob invests his, it doubles to a dollar, and then he spends it. With no capital gains tax, has Bob gotten away with something? No. Alice consumed fifty cents out of a potential dollar — a 50% bite. Bob, absent the wage tax, would have invested the full dollar and ended with two; his one dollar of actual consumption is also exactly 50% of his potential. Identical. The two are taxed at the same rate, because the only difference between them was when they chose to consume. Now add a 10% capital gains tax — levied, as it actually is, on the gain. Alice is untouched, still at 50%. Bob’s fifty cents doubles to a dollar, he pays ten percent on his fifty-cent gain — a nickel — and is left with ninety-five cents against a potential two dollars: an effective bite of 52.5%. The capital gains tax didn’t equalize Alice and Bob; it taxed Bob more, purely for the crime of waiting. The wage tax already shrank the principal both of them started from; the capital gains tax adds a second wedge that binds only on the one who postponed. The secretary-versus-billionaire comparison counts the second wedge and forgets the first — it mistakes the patient saver for a tax dodger. (None of this proves capital income must never be taxed; Bob’s return might contain luck, rent, or relabeled wages, which is exactly where next week’s essay goes.)
The same timing problem haunts the estate tax, and here, for once, the story is messy, so let me name the mess. Part of any estate is income that was already taxed in the hands of the person who earned it; taxing it again on transfer is a straightforward double-count. But part of an estate is unrealized gains that were never taxed at all — and under current law the heir’s basis is stepped up to market value at death, so those gains escape income tax entirely. That cuts both ways against the simple story: the estate tax is partly a double-count and partly the only tax those unrealized gains will ever face. The right fix isn’t to add an estate tax on top — it’s to kill the step-up, so gains are taxed exactly once, instead of either twice or never. Taxing gains once and taxing inheritance as such are two different aims, and stuffing them into one instrument hides both. (That, too, is the buy-borrow-die machinery from the Tax Alpha piece, viewed from the far end of a life.) Either way, the lesson holds: a tax on accumulated saving is usually a tax on consumption deferred across a life, or across generations, not a painless dip into a pile.
One more wedge before we leave the arithmetic, because this one belongs to the system we actually have, and I don’t want anyone walking out of this section feeling smug about realization. The current tax is levied on nominal gains. Nobody indexes your basis for inflation. So consider the most boring asset imaginable: one that merely keeps pace with the CPI, forever — zero real return, the owner never one dollar richer in purchasing power. Under a nominal-gains tax there is no such thing as “no gain.” At 3% inflation, sell after thirty years and the tax takes 14% of the asset’s entire value; after fifty years, 18%; hold long enough and the take converges to the full 23.8% — of the asset, not the gain, because at long horizons the basis shrinks toward irrelevance and the “gain” converges to the whole thing. A capital gains tax on a zero-real-gain asset is a slow confiscation of principal, at a rate that climbs with the holding period toward the headline rate itself. And for assets that do earn something real, the same mechanism silently marks up the rate: at 2% real and 3% inflation over thirty years, the 23.8% headline is an effective 41% on the gain you actually made. Same signature as before — a flat statutory rate hiding a bite that grows with the horizon — different channel: the proposals’ wedge compounds through the return; the current system’s compounds through the price level. Giesecke and Nassios just ran this arithmetic for Australia, whose effective top rate of 23.5% sits within rounding of ours by pure coincidence, and they added a design warning worth pocketing: half-indexation — recognizing real gains but real losses only when they are also nominal losses — can be worse at thirty-year horizons than not indexing at all. The moral generalizes, and it completes the fix from a moment ago: kill the step-up and index the basis — real gains, taxed exactly once. Anything else taxes either twice, never, or the inflation. Tax the gain, not the price level.
The bonfire
So the bin doesn’t exist, and to the extent it does, its contents are harmless — you cannot tax the hoard, and its mere existence is already a gift. But the intuition is bin-shaped, and it will not die until you follow it all the way down. Landsburg takes the argument to the vault. Let me take it to the match.
Suppose a billionaire wants — really wants — to give his entire fortune to the rest of the country. Not to a foundation, not to a cause, not to a board of trustees who will summer in Aspen deciding how to disburse it. To everyone, directly, with zero overhead and zero leakage. How?
Simple. Liquidate the entire net worth, convert all of it to dollars, and incinerate the cash. Strike a match. There you are. (Grant me the liquidation as a premise — yes, selling that much moves prices, and someone is on the other side of every trade. The toy model is about what happens to the claims once they’re cash, so stipulate the conversion and let’s move on.)
Stay with me, because this is rigorous, not a joke — or rather, it’s both. Money is not wealth. Money is a claim on wealth: a ration ticket entitling the bearer to some slice of the real goods and services the economy produces. The actual wealth is the goods themselves — the food, the housing, the machines, the labor. Dollars just determine who gets which slice. So when our billionaire burns his fortune in cash, he destroys his claims while leaving every real asset on earth exactly where it stood. The factories still hum. The farmland still grows wheat. Not one good has been destroyed. He has simply torn up his own ration tickets and walked away from the table.
And because the same pile of real goods is now divided among a slightly smaller stock of dollars, everyone else’s dollars are worth fractionally more. He has made a gift to every holder of the currency, in proportion to what they hold, via a whisper of deflation — no Treasury in the middle, no administrator skimming, no application filed. (This is a fixed-money thought experiment; a central bank can offset the deflation, and we’ll deal with the Fed in a moment. The toy model is here to isolate one fact, not to model the plumbing.) Every dollar-holder on earth gets a sliver, the instant the ash cools.
That is the cleanest charitable act available to a very rich man, and it requires no Giving Pledge, no press release, no naming rights on a hospital wing. Just a match.
Now hold that next to the hoarder, and watch the two nearly collapse into one. The hoarder’s unexercised claims do the identicalfavor to everyone else’s claims that burning them would — today, and every day the hoard stays a hoard. In neither case is he pulling real goods out of the common pool. The one difference between them is tomorrow: the hoarder keeps the option to march back to the table, and the burner does not. A concert ticket sitting unused in your pocket and a concert ticket torn up differ in exactly one respect — until the doors close, you might still go. So the exact statement is this: the vault and the bonfire are the same act in the present tense, and they stay the same act for every year the vault stays shut. Which still leaves the question the wealth-tax intuition can never answer: if a billionaire torching his entire fortune is a pure gift to the public, what exactly was that fortune takingfrom anyone while it sat unexercised? Holding claims you don’t cash is, for every year you don’t cash them, identical in real terms to having handed them out. The thing the tax imagines it is recovering was never being taken in the first place — only, at most, reserved.
There’s even a wrinkle that shows how specific this transfer is, in a way a blunt tax is not. The gift goes to whoever holds the currency you burn. Incinerate dollars and you’ve made a gift to dollar-holders — disproportionately Americans, but also every foreign central bank and saver sitting on Treasuries and greenbacks. Burn a globally-held currency instead of a domestically-held one and you change who receives your gift. The incidence isn’t a mystery; it follows the denomination of the ash. Subject to the central bank’s response, you can in principle steer who benefits just by choosing what you set alight — which is more than you can say for a tax, where the incidence is whatever the equilibrium decides, not whatever the legislator intended.
I’ll be honest about the size, because overclaiming here would be the same sin I’m accusing the other side of. The gift from any single bonfire is tiny and diffuse — even a vast fortune is a rounding error against the money supply, so the deflation is microscopic, smeared across hundreds of millions of holders. (You might object that a central bank targeting inflation would simply reprint to offset the deflation. But the Fed isn’t targeting the man with the match — it’s steering an aggregate, and whatever it prints flows to whoever it transacts with, in proportions having nothing to do with who burned what. That’s a separate transfer with its own incidence; it does not reach into the ash and hand the gift back. In the limiting case of a complete offset, the recapture accrues as seigniorage to the consolidated government — our billionaire would, in effect, have mailed his fortune to the Treasury by the scenic route, which is a worse joke but still a transfer. In practice the question never arises, because the burn sits so far beneath the Fed’s measurement noise that the objection is hypothetical: not a drop in the bucket, a drop in the reservoir.) So the claim is not that burning money is a large transfer. It is that the transfer is clean, leakage-free, and real — and that its smallness is of a piece with the rest of this story. The magnitudes are modest. The direction is the entire argument.
One more thing before the coda, because I can hear the objection forming: the serious literature does not say the optimal capital tax is zero, and you haven’t dealt with it. Correct, and next week I deal with all of it, at full strength — Chamley and Judd’s famous result and the corrections that bent it; the strongest wealth-tax model in the literature, which deserves far better than a footnote; the one argument for taxing capital that I cannot refute and won’t pretend to; what Sweden learned in 1984, at the price of an entire estate; and two Berkeley economists whose errors all point, mysteriously, in the same direction.
Next week: Scrooge McDuck Goes to Stockholm. No, he doesn’t get a Nobel.
If you found the terminal-accounting move useful, it’s the same one I ran on the wealth-management industry in The Conservation Law of Tax Alpha — different pile, same conserved quantity, same trick for finding where it went.
This piece is one argument out of a book’s worth I’ve already written up — a whole manuscript of economics done this way, from first principles, following the arithmetic wherever it goes. If you happen to be a literary agent and any of this is your kind of thing, get in touch. I have no appetite for firing proposals into the void; the void, as far as I can tell, is managing perfectly well without them.
My book, The Science of Free Will, asks an equally uncomfortable question about an equally cherished story. For the India series, start with The Paradox of India and the full collection; for Britain’s long institutional decline, first seen in 1979, there’s Albion.
Ok, I see your point now. Your argument is internally consistent. But it measures from a baseline the post never defends. "Anything that increases your wealth is income" is the Haig-Simons definition — a definition, not a theorem. Definitions choose tax bases; they cannot tell you which base is right. Once you define income to include accruals, deferral becomes a zero-interest loan, realization becomes a subsidy, and a loss year becomes forgiveness — all true relative to that baseline. Whether that baseline is the neutral one is the entire question. The arithmetic says it is not: an annual tax on accruals is a tax on waiting, and a flat rate on waiting compounds. Today's 23.8%, applied annually to a 5% real return, removes 37% of a working life's deferred consumption and two-thirds of a century's. Measured from the consumption baseline, the picture inverts exactly — accrual taxation is not the calling-in of a subsidized loan; it is a demand for prepayment on meals not yet eaten, with the compounding wedge as the interest charged. Both frames are coherent. Adjudicating between them is what the optimal-tax literature exists to do — and note that the benchmark result of that literature is that the correct rate on capital is zero, with the later corrections finding positive optima that are contested in size and, in every serious model, priced against the wedge as a first-order cost. Zero is still on the table. It has never left the table.
On one issue, I would go further than you — conditionally. The convexity you describe — appreciate and the loan grows, die and it is forgiven — is real and indefensible. But its source is step-up at death and buy-borrow-die, not realization itself. So what I say is this: if capital is to be taxed at all, then real gains, indexed, taxed exactly once at sale, dominates both the system we have and the mark-to-market machinery — no annual valuations of private companies, no bills on unsold assets, no refunds mailed to billionaires in crash years, no taxing of phantom inflation. Whether the rate on that best-designed base should be 15%, 5%, or zero is exactly what the models fight about, and the most reasonable reading of that fight is: low, possibly all the way down to zero.
On arbitrage: taxing every accretion identically does close the relabeling door — but arbitrage-freeness alone proves too much, since a 100% tax on everything is also arbitrage-free. The relabeling problem puts a floor under the capital rate; it does not raise the floor to the labor rate, and how low that floor can sit is a question of legal drafting, not economics. Draft well and the floor may sit very near the ground if not on it.
The whole game is tax free compounding - run the numbers on Buffett. Letting Capital earn returns on zero interest loans from the taxpayer is absurd